
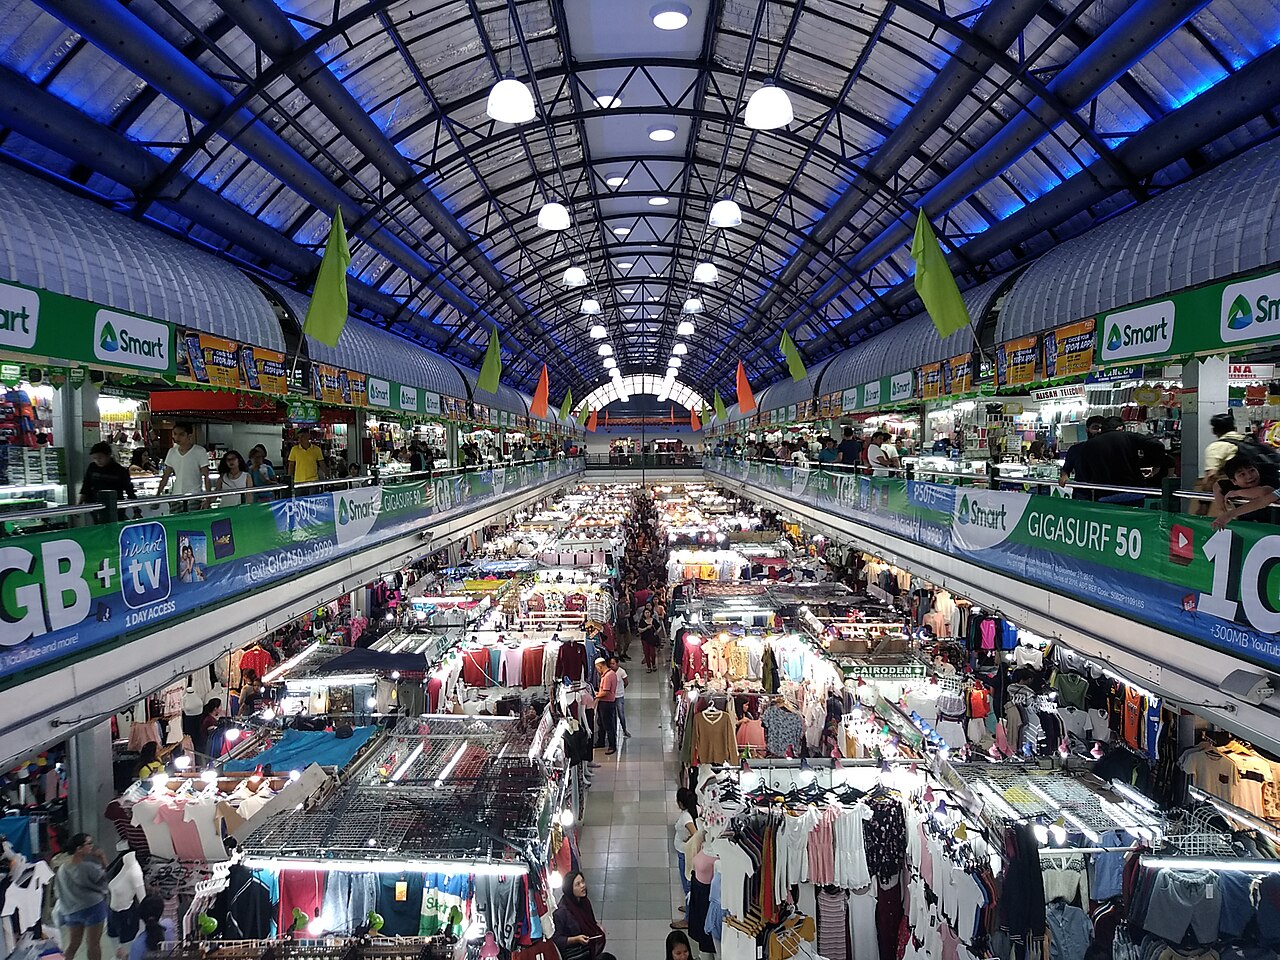
This report offers a snapshot of the current international retailer landscape within Metro Manila.
This article reviews Cushman & Wakefield’s March 2015 study of international retailers in Metro Manila. The study tracked 190 foreign brands that entered the Philippines or opened their first dedicated stores between 2008 and 2014. Figures and forecasts below reflect the market at the time of publication.
International retailer activity increased during the study period, with at least 45 brands entering the country in 2014, according to Cushman & Wakefield. A young population, rising incomes and the availability of shopping mall space supported retailer interest.
The report put average Philippine GDP growth at 6.7% over the three years preceding publication. Services continued to expand alongside a recovering manufacturing sector. Household consumption accounted for approximately 69–72% of GDP over the six years reviewed.
Cushman & Wakefield identified business process outsourcing (BPO) and remittances from overseas Filipinos as important sources of employment and household income. Both supported the report’s assessment of consumer demand and the country’s appeal to international retailers.
The report cited annual population growth of 1.9% between 2000 and 2010 and estimated that the Philippine population had passed 100 million in July 2014. It linked the country’s demographic profile and urbanization to demand for a wider range of products and services.
BPO employment stood at approximately 900,000 at the end of 2013, according to the report. Income from the sector and overseas remittances helped support household spending. The study also associated increasing urban consumption with shopping mall development across the country.
Cushman & Wakefield estimated Metro Manila’s shopping mall stock at 6.5 million square meters in March 2015. It forecast an increase to 7 million square meters by 2017 as projects in mixed-use districts were completed.
The firm’s 2014 Main Streets Across the World survey ranked the Philippines 62nd by the rent of its most expensive retail location. The ranking compared selected prime retail locations across countries. The report identified relatively competitive rents as an additional incentive for foreign retailers.
International retailers commonly worked with local partners, including Stores Specialists, Inc., SM Group, Robinsons Retail and Bench’s parent company, Suyen Corporation. These arrangements gave brands access to local operating experience, distribution and property networks.
Wholly foreign-owned operations offered another route. Under the Retail Trade Liberalization Act of 2000, qualifying retailers could establish wholly owned businesses, subject to capital requirements and other eligibility conditions.
The report also noted proposals to amend restrictions on foreign participation. Those proposals formed part of its outlook for future retailer entry; they were not enacted changes established by the study.
Mid-range food and beverage and clothing brands lead new retailers
Mid-range brands accounted for approximately 79% of the foreign brands tracked in the report. Food and beverage and clothing were prominent categories.
Fashion retailers such as Forever 21, Cotton On and UNIQLO occupied larger units, while food and beverage operators including BonChon, Happy Lemon and J.CO Donuts & Coffee expanded through smaller outlets.
H&M’s first Philippine store provided a specific example of the fashion format. It opened at SM Megamall on October 17, 2014, with approximately 3,000 square meters across three floors, according to H&M. UNIQLO had opened its first Philippine store at SM Mall of Asia in June 2012; its launch announcement specified approximately 1,550 square meters of sales floor.
Luxury and high-end retail also featured in the study, with brands including Hermès, Stuart Weitzman and Casadei. The report highlighted dedicated watch boutiques at Central Square in Bonifacio Global City, including Hublot, Baume & Mercier, Breitling, Tudor, IWC and Jaeger-LeCoultre.
Benefit and Clinique opened their first dedicated Philippine stores in 2011 and 2012, respectively, according to the report. Other established brands introduced flagships in newly completed shopping centers.
The report identified approximately 123 brands from North America and Europe. American names included Aéropostale, American Eagle Outfitters, Jamba Juice, Joe’s Jeans, Old Navy, Papa John’s and Payless ShoeSource.
European brands represented in the study included Alexander McQueen, H&M, Burton Menswear London, Stefanel and UNOde50, with France, Italy and the UK prominent among their countries of origin.
Asian retailers accounted for approximately 56 brands and 261 stores in Metro Manila. The corresponding store counts were 158 for North American brands and 157 for European brands. Cushman & Wakefield attributed the Asian store total partly to the number of food and beverage chains in the group.
Japan contributed at least 22 brands during the study period. Examples included MUJI, Royce’, Sony, St. Marc Café and UNIQLO. Australian and Middle Eastern names included Cotton On, F&X, Patchi, Rubi and Typo.
Makati, Mandaluyong and Quezon City accounted for approximately 60% of the stores operated by the tracked brands. The report associated this concentration with the availability of shopping mall space in those cities.
Flagships followed a somewhat different distribution. The study identified at least 106 across Mandaluyong, Taguig and Makati. Examples included Bershka, Stradivarius, INGLOT and Jimmy Choo in Makati; Carven, Crate & Barrel, Forever 21, H&M and Hervé Léger in Mandaluyong; and Casadei, Ever New, Hamleys, Jamba Juice, Joseph and Pottery Barn in Taguig.
The report recorded fewer stores from its tracked brands in San Juan, Las Piñas, Marikina, Parañaque and Pasig. It linked this pattern to the supply of new mall space and proximity to other established retail destinations.
Luxury and high-end brands in the cohort were concentrated in Mandaluyong and Makati, with a more limited presence in Quezon City and Muntinlupa. The study discussed surrounding residential and business catchments as possible explanations.
Sustained demand and renewed interest from new and existing retailers
The report identified continued interest from international retailers through partnerships with local operators and commitments to shopping mall space. It also noted examples of foreign brands replacing existing tenants.
Robinsons Retail announced in 2014 that it would bring Costa Coffee to the Philippines. At the time of the March 2015 report, this was an announced market entry.
Existing and returning brands also contributed to activity. The report cited additional stores from Nanbantei of Tokyo and Eddie Bauer, and Baskin-Robbins’ return to the Philippines in 2014 with a store at Central Square in Bonifacio Global City.
Compare 18 open-air malls, retail parks and enclosed projects across the US, Europe, Asia and the Middle East, with sizes,…
The vendors and deployments behind shopping advice, store navigation and retail operations, with a closer look at what it takes…
Miss A, Rowan and HEYTEA are on US mall opening lists in fall 2026. Their public records show what each…
Gross margins and selected profit metrics for Coach, Pop Mart, lululemon, Miniso, Five Below, TJX and Costco, plus where each…
NikeSKIMS, Birkenstock and Starbucks Reserve chose HKRI Taikoo Hui for major China debuts. Why the Shanghai complex keeps winning new…
Bluewater opens its first new anchor since 1999. Next takes the former House of Fraser space with about 132,000 square…
